
National Atomic Company “Kazatomprom” JSC (“Kazatomprom”, “KAP” or the “Company”) announces the following operations and trading update for the third quarter and nine months ended 30 September 2026.
This update provides a summary of recent developments in the uranium industry, as well as provisional information related to the Company’s key third quarter and nine months operating and trading results. The information contained in this Operations and Trading Update may be subject to change.
Market Overview
The Lindsey O. Graham Sanctioning Russia and Iran Act of 2026 (H.R. 5334), signed into law on 18 September, provides for broad economic and trade restrictions, including provisions on Russian uranium imports. However, before these measures took effect, the US President, via Executive Order 14436 on 16 October 2026, pursuant to Section 115(a) of the Act, granted national interest waivers, suspending the operation of most of the Act’s sanction provisions regarding Russia, including Section 111, as well as the import duties provided for under Sections 112 and 113.
The United States and the Kingdom of Saudi Arabia signed a 30-year civil nuclear cooperation agreement (the “123 Agreement”) and an accompanying bilateral safeguards agreement, opening the way for exports of US nuclear technology to Saudi Arabia. The agreement provides for a two-year Joint Enrichment and Conversion Study to assess the potential for uranium enrichment in Saudi Arabia; and any future enrichment would require the written consent of both parties. In late August, the US President formally submitted the agreement to Congress, triggering the mandatory 90-day congressional review period.
The United States and South Korea agreed on a non-binding framework under which South Korea will invest up to $120 billion in new US nuclear capacity. The plan provides for the construction of eight reactors in the US: six Westinghouse AP1000 units and two Korean APR1400 units. Of the total amount, $100 billion is earmarked for construction costs, while $20 billion is set aside as a contingency reserve. Under the framework, Korean investors would also acquire a 5% to 10% minority stake in Westinghouse Electric Company in anticipation of a potential initial public offering (IPO).
Westinghouse Electric Company has submitted a draft registration statement on Form S-1 to the US SEC for its proposed IPO. The number of shares and the price range have not yet been determined. Westinghouse is currently owned jointly by Brookfield (51%) and Cameco (49%).
Niger signed a new Mining Convention with the Australian company Atomic Eagle for the Madaouela uranium project. Under the restructured joint venture, Madaouela Mining Company SA (MAMICO), the State’s interest increases to 40%, while Atomic Eagle will hold the remaining 60% and retain operational control.
The Italian Senate gave final approval to legislation enabling the country’s return to nuclear power after a 39-year moratorium. The law mandates the government to establish a regulatory and safety framework for civil nuclear energy within 12 months. The law explicitly provides for small modular reactors (SMRs) and advanced modular reactors (AMRs). Italy’s national energy plan envisages 8–16 GW of nuclear capacity by 2050, which is estimated to meet 11% to 22% of the country’s electricity demand.
Kazakhstan Nuclear Power Plants LLP and Atomstroyexport JSC (part of Rosatom) signed the primary contract for the construction of Kazakhstan’s first nuclear power plant, the Balkhash NPP. The contract covers design, equipment supply, and construction.
The following events underscored key developments on the demand side during the reporting period:
- Unit 3 of the Changjiang NPP in Hainan, China, entered commercial operation. This marks the first of two Hualong One (HPR1000) reactors built as Phase II of the Changjiang NPP, a joint venture between China Huaneng (51%) and CNNC (49%).
- EDF extended the expected operating lifetimes of the Heysham 1 and Hartlepool NPPs in the UK by two years to March 2030, from previously scheduled March 2028.
- Spain renewed the operating license of the Almaraz NPP until June 2030, following a favorable report from the Nuclear Safety Council (CSN). Under the country’s nuclear phase-out policy, Unit 1 had originally been scheduled to shut down in November 2027, followed by Unit 2 in October 2028.
- The US Department of Energy finalized a loan of up to $1.9 billion to NextEra Energy to support the restart of the Duane Arnold Energy Center. Subject to Nuclear Regulatory Commission (NRC) approval, the restart is expected in late 2028 or early 2029.
On the supply side:
- NexGen Energy began construction of the Rook I project in northern Saskatchewan, Canada. Construction is expected to take four years, with average life-of-mine production estimated at ~8,346 tU (21.7 million lbs) per year, and a permitted capacity of up to 11,538 tU (30 million lbs) per year.
- Paladin Energy completed the ramp-up of its 75%-owned Langer Heinrich mine in Namibia. The mine produced ~1,854 tU (4.82 million lbs) in twelve-month period ended 30 June 2026 (FY2026).
- Botswana granted Orano Mining three new uranium prospecting licenses valid until March 2029, bringing the Orano group’s total number of licenses in the country to 18.
- The US International Development Finance Corporation (DFC) approved up to $414.2 million in conditional debt financing for the development of the Dasa greenfield uranium project in Niger. The project is operated by SOMIDA, which is owned 80% by Canada’s Global Atomic and 20% by the Government of Niger.
- Boss Energy increased production at its Honeymoon project in South Australia by 61% year-on-year to ~542 tU (1.41 million lbs) for the twelve-month period ended 30 June 2026 (FY2026). The company also released an updated life-of-mine plan for Honeymoon, forecasting total production of ~5,308 tU (13.8 million lbs) over a nine-year mine life.
Market Pricing and Activity
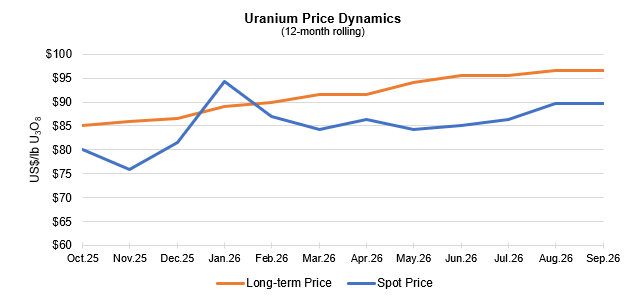
* Average of UxC and TradeTech reported month-end spot and long-term prices
Activity on the spot market in July was moderate, which is typical for the summer period, while the weekly spot price rose from $85.00/lb to $86.30/lb of U3O8 by the end of the month. In August, the price continued to rise, reaching $89.40/lb in the last week of the month. This increase was supported by limited spot availability, a cluster of utility requests for proposals (RFPs), and a seasonal pickup in activity ahead of the World Nuclear Symposium. According to third-party analysis, spot activity in September was among the lowest seen in many years; nevertheless, the price reached its quarterly high of $90.10/lb in mid-September.
According to third-party estimates, spot volumes in the first nine months of 2026 rose by 26% year-on-year to ~15,270 tU (39.7 million lbs), up from ~12,080 tU (31.4 million lbs) in the same period of 2025, while the average weekly spot price increased by 22% to $86.55/lb from $70.91/lb of U3O8.
In August, the long-term price, published monthly by third-party sources, reached an all-time high of $96.50/lb, reflecting growing uncovered demand and supply-side constraints. Term contracting volumes in the first nine months of 2026 totaled ~16,230 tU (42.2 million lbs), comparable to ~16,920 tU (44.0 million lbs) in the same period of 2025.
Company Developments
Exploration Rights for the Kyzyltu Block
On 21 September, Kazatomprom announced that it had obtained a subsoil use license for uranium exploration at the Kyzyltu block in Kyzylorda region. The license grants the Company a right to explore the block for a period of six years. According to preliminary estimates, uranium resources at the block could amount to approximately 10,000 tU (~26.0 million pounds U3O8). Exploration work is planned to commence in the near term to further assess the resources and evaluate the block’s potential.
The license is part of the Company’s ongoing exploration program, reflecting Kazatomprom’s key strategic priorities of efficiently using and replenishing its resource base.
Credit Ratings
On 25 August, Fitch Ratings affirmed Kazatomprom’s credit rating at “BBB”, outlook “Stable”. Fitch rates the Company on a standalone basis under its Government-Related Entities Rating Criteria, reflecting limited ties with its ultimate majority shareholder, the Republic of Kazakhstan (“BBB”/Stable), which indirectly owns 75% of the Company’s shares.
On 8 September, Moody’s affirmed Kazatomprom’s long-term issuer rating at “Baa1” and upgraded its Baseline Credit Assessment (BCA) from “baa3” to “baa2”. The outlook remains “Stable”. The BCA upgrade reflects the Company’s proven track record of strong operating and financial performance, high profitability, and robust liquidity. It also highlights its conservative financial policies, strong credit metrics and a net cash position maintained throughout the uranium price cycle.
Kazatomprom Mine Tour
On 6-7 October, the Company held its annual mine tour for investors and analysts, welcoming participants from around the world. The itinerary included visits to the operations at Appak and Ortalyk joint ventures in Turkestan region, where participants observed the full cycle of ISR uranium production and processing, as well as the Company’s adherence to leading environmental and social standards across its operations.
The tour provided the investment community with direct engagement with site management and operational teams, offering first-hand insight into Kazatomprom’s operations. It reaffirmed the Company’s position as a reliable, ESG-compliant supplier of natural uranium operating in a low-risk jurisdiction.
Kazatomprom’s 2026 Third-Quarter and Nine-Months Operational Results1
|
|
|
Three months ended 30 September |
|
Nine months ended 30 September |
|
||
|
|
|
2026 |
2025 |
Change |
2026 |
2025 |
Change |
|
Production volume U3O8 |
tU |
7,216 |
6,467 |
12% |
20,508 |
18,709 |
10% |
|
Mlbs |
18.76 |
16.81 |
53.32 |
48.64 |
|||
|
Production volume U3O8 |
tU |
3,915 |
3,381 |
16% |
10,969 |
9,812 |
12% |
|
Mlbs |
10.18 |
8.79 |
28.52 |
25.51 |
|||
|
Group U3O8 sales volume4 |
tU |
6,444 |
5,151 |
25% |
14,030 |
12,776 |
10% |
|
Mlbs |
16.75 |
13.39 |
36.48 |
33.22 |
|||
|
KAP U3O8 sales volume (incl. in Group)5 |
tU |
4,220 |
4,124 |
2% |
10,303 |
11,111 |
(7%) |
|
Mlbs |
10.97 |
10.72 |
26.79 |
28.89 |
|||
|
Group average realized price6 |
USD/lb U3O8 |
81.50 |
68.78 |
18% |
73.51 |
62.97 |
17% |
|
KAP average realized price7 |
USD/lb U3O8 |
79.45 |
67.75 |
17% |
70.19 |
61.37 |
14% |
|
Average month-end spot price8 |
USD/lb U3O8 |
88.56 |
76.28 |
16% |
87.41 |
71.68 |
22% |
Production on both a 100% and an attributable basis increased during the first nine months of 2026 compared to the same period in 2025, due to a higher 2026 production plan in line with the Company’s guidance and Subsoil Use Agreements’ requirements for 2026.
For the nine months of 2026, sales volume at the Group level showed a 10% increase compared to the same period in 2025, which is attributed primarily to the anticipated production ramp-up at certain JVs and the timing of delivery requests from those JVs’ second participants. Comparatively lower sales volumes at KAP-level are attributable purely to delivery schedules and timing of such requests from customers. Sales volumes can vary significantly each quarter, and quarterly sales results can vary from year to year due to flexible customer request timelines throughout the year as per specifics of uranium business.
For the nine months of 2026, the Group and KAP average realized prices grew by 17% and 14%, respectively, compared to the same period in 2025 showing strong correlation with the spot price, which rose by 22% year-on-year. It is worth noting that over the shorter three-month period, our average realized prices accelerated to outpace the broader spot market performance: Group and KAP realized prices grew by 18% and 17%, respectively, beating the 16% increase in the spot price. The Company’s current sales portfolio includes long-term contracts linked to uranium spot prices, however, certain deliveries under long-term contracts incorporate a portion of fixed pricing components, including price ceilings, which were negotiated during a different pricing environment.
In the uranium market, the trends in quarterly metrics and interim results are rarely representative of annual expectations; for annual expectations, please see the Company’s guidance metrics, as well as its price sensitivity table from section 10.1 Uranium sales price sensitivity analysis, in the Company’s Operating and Financial Review of six months ended 30 June 2026.
Kazatomprom’s 2026 Reiterated Guidance
|
|
Guidance for 2026 |
|
|
|
|
490 KZT / USD |
|
Production volume U3O8 (100% basis)1 |
tU |
27,500 – 29,000 |
|
Mlbs |
71.49 – 75.39 |
|
|
Production volume U3O8 (attributable basis)2 |
tU |
14,500 – 15,500 |
|
Mlbs |
37.70 – 40.30 |
|
|
Group sales volume (consolidated)3 |
tU |
19,500 – 20,500 |
|
Mlbs |
50.70 – 53.30 |
|
|
Incl. KAP sales volume |
tU |
13,100 – 14,100 |
|
Mlbs |
34.06 – 36.66 |
|
|
Revenue – consolidated5 |
KZT bln |
2,100 – 2,200 |
|
Revenue from Group U3O8 sales5 |
KZT bln |
1,900 – 2,000 |
|
C1 cash cost (attributable basis)* |
USD/lb |
25.50 – 27.00 |
|
All-in sustaining cash cost |
USD/lb |
39.00 – 40.50 |
|
Total capital expenditures of mining entities (100% basis)6 |
KZT bln |
435 – 450 |
All 2026 guidance metrics remain unchanged. However, Revenue, C1 cash cost (attributable basis), and All-in Sustaining cash cost (attributable C1 + capital cost) may vary from the guided ranges to the extent that the USD/KZT exchange rate and uranium spot price deviate from the Company’s baseline assumptions.
For more information, please contact:
Investor Relations Inquiries
Botagoz Muldagaliyeva, Director of Investor Relations
Tel: +7 (7172) 45 81 80 / 69
Email: ir@kazatomprom.kz
Public Relations and Media Inquiries
Daniyar Oralov, Director of Public Relations
Tel: +7 (7172) 45 80 63
Email: pr@kazatomprom.kz
About Kazatomprom
Kazatomprom is the world’s largest producer of uranium, with the Company’s attributable production representing approximately 20% of global primary uranium production in 2025. The Group benefits from the largest reserve base in the industry and operates, through its subsidiaries, JVs and Associates, 27 deposits grouped into 14 mining assets. All of the Company’s mining operations are located in Kazakhstan and extract uranium using ISR technology with a focus on maintaining industry-leading health, safety, and environment standards.
Kazatomprom securities are listed on the London Stock Exchange and Astana International Exchange. Kazatomprom is the national atomic company in the Republic of Kazakhstan. The Group’s primary customers are operators of nuclear power plants, the principal export markets for the Group’s products are countries in Asia, Europe, and the Americas. The Group sells uranium and uranium products under long-term contracts, short-term contracts, as well as in the spot market, directly from its headquarters in Astana, Kazakhstan, and through its Switzerland-based trading subsidiary, TH Kazakatom AG (THK).
For more information, please see the Company’s website at www.kazatomprom.kz.
Forward-looking statements
All statements other than statements of historical fact included in this communication or document are forward-looking statements. Forward-looking statements give the Company’s current expectations and projections relating to its financial condition, results of operations, plans, objectives, future performance and business. These statements may include, without limitation, any statements preceded by, followed by or including words such as “target,” “believe,” “expect,” “aim,” “intend,” “may,” “anticipate,” “estimate,” “plan,” “project,” “will,” “can have,” “likely,” “should,” “would,” “could” and other words and terms of similar meaning or the negative thereof. Such forward-looking statements involve known and unknown risks, uncertainties and other important factors beyond the Company’s control that could cause the Company’s actual results, performance or achievements to be materially different from the expected results, performance or achievements expressed or implied by such forward-looking statements. Such forward-looking statements are based on numerous assumptions regarding the Company’s present and future business strategies and the environment in which it will operate in the future. THE INFORMATION WITH RESPECT TO ANY PROJECTIONS PRESENTED HEREIN IS BASED ON A NUMBER OF ASSUMPTIONS ABOUT FUTURE EVENTS AND IS SUBJECT TO SIGNIFICANT ECONOMIC AND COMPETITIVE UNCERTAINTY AND OTHER CONTINGENCIES, NONE OF WHICH CAN BE PREDICTED WITH ANY CERTAINTY AND SOME OF WHICH ARE BEYOND THE CONTROL OF THE COMPANY. THERE CAN BE NO ASSURANCES THAT THE PROJECTIONS WILL BE REALISED, AND ACTUAL RESULTS MAY BE HIGHER OR LOWER THAN THOSE INDICATED. NONE OF THE COMPANY NOR ITS SHAREHOLDERS, DIRECTORS, OFFICERS, EMPLOYEES, ADVISORS OR AFFILIATES, OR ANY REPRESENTATIVES OR AFFILIATES OF THE FOREGOING, ASSUMES RESPONSIBILITY FOR THE ACCURACY OF THE PROJECTIONS PRESENTED HEREIN. The information contained in this communication or document, including but not limited to forward-looking statements, applies only as of the date hereof and is not intended to give any assurances as to future results. The Company expressly disclaims any obligation or undertaking to disseminate any updates or revisions to such information, including any financial data or forward-looking statements, and will not publicly release any revisions it may make to the Information that may result from any change in the Company’s expectations, any change in events, conditions or circumstances on which these forward-looking statements are based, or other events or circumstances arising after the date hereof